lend.ezee
The Enterprise Loan Origination System
That Launches Products in Weeks
100% No Code. AI-Powered.
From retail to commercial loan origination systems, orchestrate every step of the lifecycle.
Automate decisioning, ensure compliance, and deploy new products instantly.

Every Stage. AI Handles It.
From lead qualification to disbursement, every step of origination is handled by a specialized AI agent working in concert.

Every origination stage, connected
From pre-login to disbursement, connect every stage of lending journey on one intelligent, no-code platform
Lead & Pre-Qualification
- AI lead scoring
- Junk lead filtering
- Lead enrichment
KYC & Compliance
- eKYC, VKYC
- CKYC checks
- AML & sanctions screening
Document Intelligence
- 50+ document types
- Auto-classification
- Extract, validate & detect
Credit Analysis
- Financial analysis
- Multi-signal insights
- Risk assessment
Decisioning & Approval
- Policy-based decisioning
- Audit trail
- Faster approvals
Sanction & Communication
- Auto-generated sanction letters
- Secure delivery
Readiness Checks
- Account validation
- Disbursement orchestration
- Compliance checks

Build Any Loan Product Without
Writing Code
Type in plain English. AI generates fields, layouts, validations, and compliance checks automatically. Business teams self-serve.
More Approvals. More Members.
More Growth.
Conversational AI qualifies prospects in real-time routing only creditworthy leads into origination. Build once, deploy everywhere.


Intelligence Built Into Every Step of Verification.
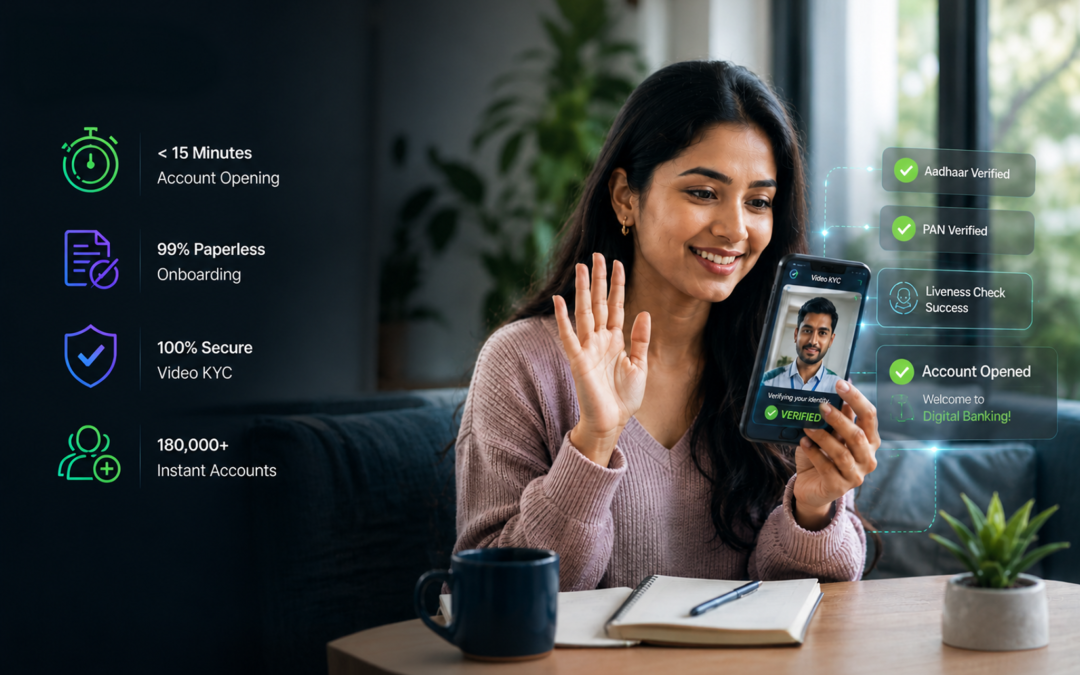
Live face detection, OCR-based ID extraction, geo-location capture, and digital forgery checks – all in a three-step mobile flow. No branch visits. No wet signatures.
Liveness detection on every session. Digital forgery check on every document. Full geo-authenticated audit trail.
Pre-Built. Production-Proven. LOS-Agnostic.
Integrates with any stack via REST APIs, webhooks, or database connectors. Zero lock-in.
500+ Years of Banking Expertise.
One Platform.
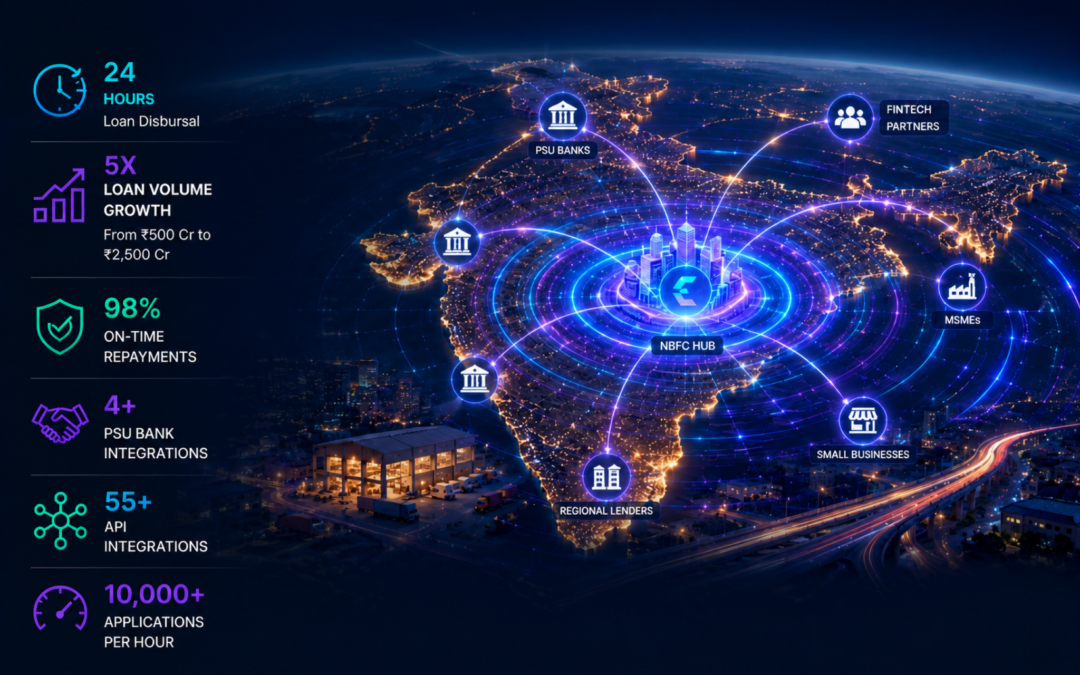
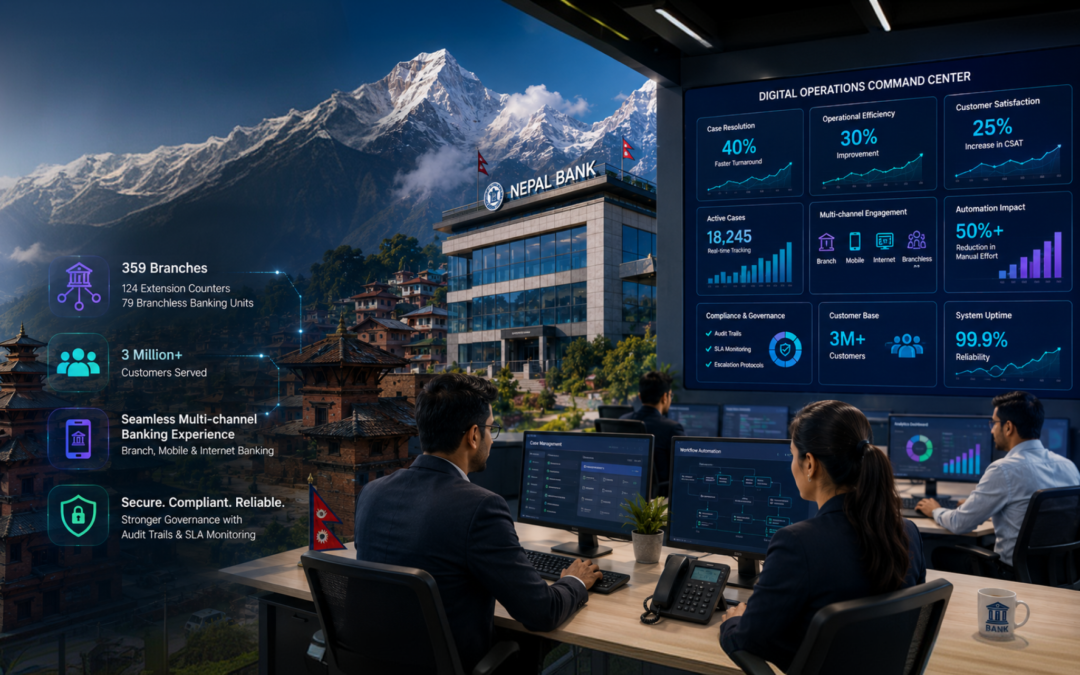
Proven at scale across 4 continents
Trusted by 100+ Banks & NBFCs Across Segments
9/28 RRBs in India Run on ezee.ai
 ```
Kickoff to Live Loans in
3–4 Weeks
Week 1
Discover
Map products, journeys, rules, and integrations.
Week 2
Build
AI generates screens. Credit policies ingested.
Week 3
Test
UAT, simulation, compliance validation.
Week 4
Go-Live
Production deployment. AI self-optimization begins.
How lend.ezee Compares
| Capability |
|
Traditional LOS | Standalone Digital | Global Platforms |
|---|---|---|---|---|
| 100% No-Code | ✓ Full | ✗ Heavy coding | ~ Partial | ~ Limited |
| 12 AI Agents | ✓ Production-live | ✗ None | ~ Basic ML | ~ Emerging |
| Go-Live Speed | ✓ <28 days | ✗ 6–12 mo | ~ 2–4 mo | ✗ 6–18 mo |
| Full Lifecycle | ✓ LOS+BRE+LMS+Collect | ~ LOS only | ~ LOS only | ~ Broad, rigid |
| Sub-100ms Decisions | ✓ Proven | ✗ Batch | ~ Limited | ~ API-dep |
| SHAP Explainability | ✓ Every decision | ✗ N/A | ✗ N/A | ~ Emerging |
The Full Credit Lifecycle. One Unified Ecosystem.
ORIGINATE
AI + No-Code LOS
Capture leads, run KYC, build journeys. 12 AI agents.
DECIDE
AI-Powered BRE
Author rules in minutes.
Sub-100ms. Audit-ready.
MANAGE
Servicing & Lifecycle
Real-time servicing.
Multi-product. NPA-ready.
RECOVER
Agentic AI Recovery
Predict, engage, resolve. Autonomously at scale.
Frequently Asked Questions
What is a loan origination system and where does it sit in the lending lifecycle?
A loan origination system automates loan processing from application to funding, positioned early in the lending lifecycle before servicing. It handles intake, verification, underwriting, and decisioning via rule engines and APIs. For MSME lenders, this cuts manual handoffs when pulling CIBIL scores or CKYC data.
What are the key stages handled by a modern loan origination workflow?
Modern LOS workflows cover pre-qualification, application intake, document verification, underwriting, approval, processing, and funding. Each stage uses automation like OCR for docs and real-time bureau pulls. In practice, SME loans move from online app to disbursal in hours, not weeks.
What role does automation play in reducing loan approval turnaround time?
Automation slashes loan TAT by 60% through straight-through processing and real-time checks, per HDFC implementations. It eliminates manual data entry via OCR and API pulls during underwriting. Lenders see approvals drop from weeks to minutes for low-risk SME cases.
How do loan origination systems support multiple loan products on a single platform?
LOS platforms manage diverse products like personal, vehicle, and MSME loans via configurable rule engines and unified data models. One workflow adapts eligibility checks across products without silos. This lets lenders cross-sell during intake, boosting portfolio efficiency.
How do lenders evaluate loan origination platforms for speed, compliance, and scale?
Lenders prioritize API-first integration for speed, built-in compliance checks for regs like RBI, and cloud scalability for volume. They test TAT via pilots and audit trails for KYC/AML. Thresholds include handling 5M+ apps yearly without downtime.
What criteria matter most when shortlisting a loan origination system for enterprise rollout?
Key criteria are modularity for custom rules, pre-built bureau/KYC integrations, and ISO/SOC compliance certifications. Enterprise focus hits 2-4 week go-lives for SaaS. Stability trumps cost for high-volume MSME operations.
How long does it typically take to implement and stabilize a loan origination system?
Enterprise LOS rollout takes 2-12 weeks, with no-code SaaS at 5-7 days and full configs at 6-12 weeks. Phased pilots stabilize workflows via testing integrations. MSME lenders hit steady state post-training in under a month.
How does a loan origination system automate borrower onboarding and application intake?
LOS automates onboarding via digital portals with OCR doc extraction and pre-filled forms from APIs. It triggers e-signatures and checklists for missing KYC. Borrowers upload once; system validates rules before underwriting.
How do loan origination systems integrate with credit bureaus and KYC providers?
LOS pulls real-time CIBIL/CKYC data via APIs during intake, normalizing scores for decision engines. KYC adds biometric/liveness checks and sanctions screening. This ensures fraud-free underwriting without manual pulls.
How do loan origination systems enforce regulatory compliance across geographies?
LOS embeds geo-specific rules like RBI digital lending or EBA guidelines into workflows with auto-flags and audit trails. It validates apps against AML/KYC in real-time. Multi-region ops adapt via configurable policies per jurisdiction.
Is Your LOS Ready for AI-Native Lending?
Each "yes" is a sign your current setup may be holding you back.
Select the statements that apply to your institution.
Your Next Loan Product Could Be Live
in 3 Weeks
Get a live walkthrough with your products, your volumes, your risk profiles. We’ll quantify the exact impact, before you commit.
Case Studies News Blogs