Turning Collections into a Strategic Advantage
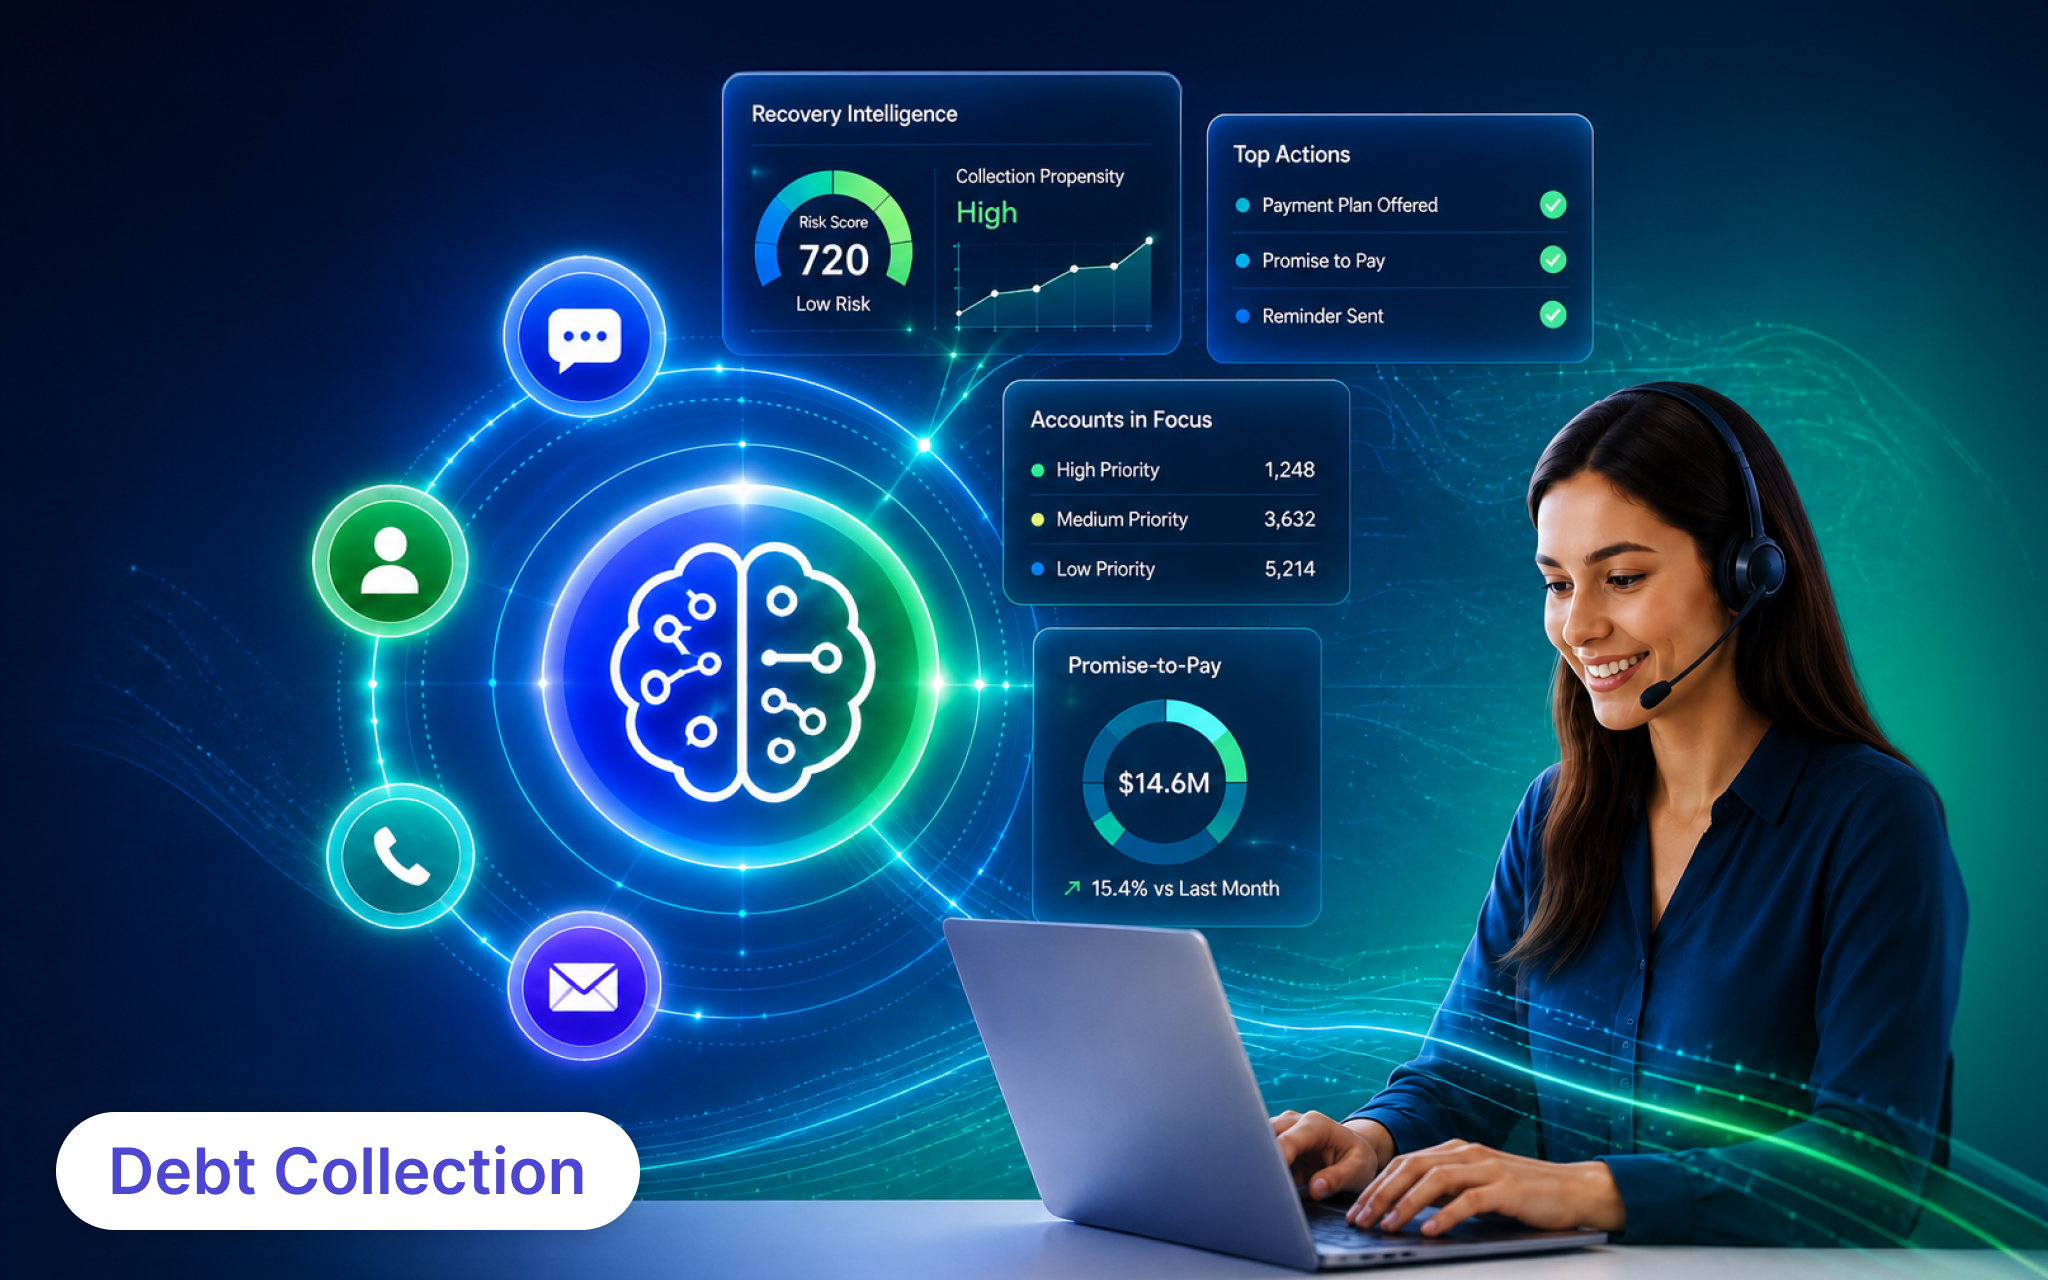
Debt collection software for banks is no longer just a backend tool. It is becoming a strategic capability that can help banks move from reactive recovery to more intelligent, scalable, and borrower-focused collections.
As financial institutions embrace digital transformation across the lending lifecycle, collections are increasingly being brought into the same technology and operating model. This creates opportunities to improve operational efficiency, borrower engagement, and recovery performance while maintaining stronger control over the collections process.
Today’s banking leaders are looking beyond the question of how to chase overdue accounts faster. The larger challenge is how to build scalable, ethical collections processes that improve recovery outcomes while protecting borrower relationships and regulatory compliance.
This evolution is being supported by a new generation of debt collection software built specifically for banks. These platforms bring together intelligence, automation, and compliance to automate repetitive tasks, personalise borrower communication, and provide greater control across the collections lifecycle, from early-stage reminders to complex recovery workflows.
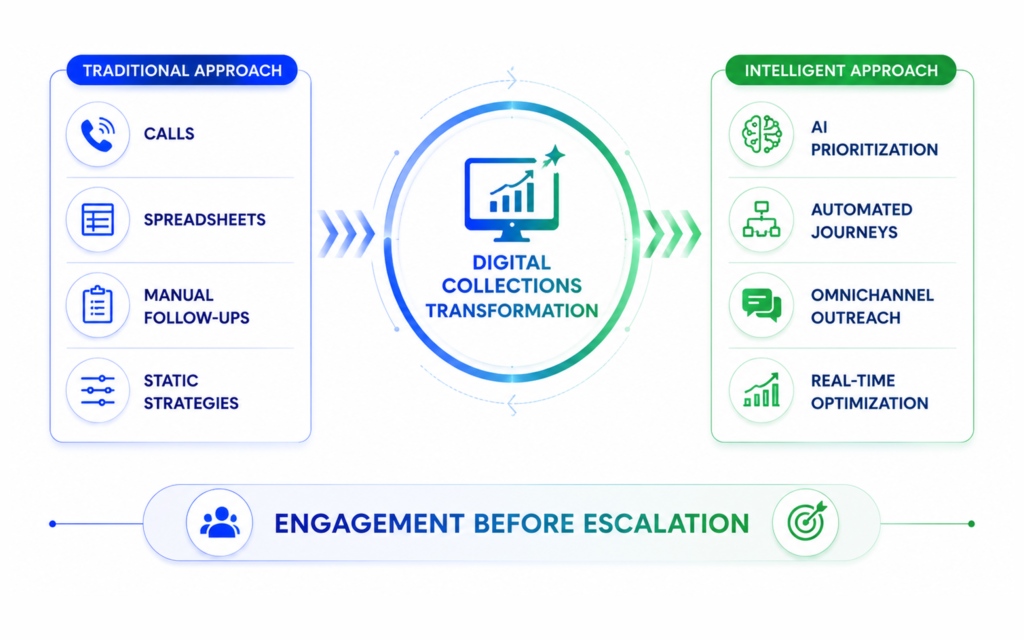
The shift is no longer speculative it’s strategic.
Nearly 70% of banking transformation leaders globally now view collections as a “strategic capability” rather than an operational burden. This shift is reflected in market data showing the global debt collection services market projected to reach $38.67 billion by 2033, growing at a 3% CAGR from 2025. That mindset shift alone is transforming how collections is planned, funded, and measured across the industry.
The potential outcomes are broader than recovery alone: faster resolution, lower operational effort, better borrower engagement, and stronger control over collections activities.
In this deep dive, we’ll explore how banks can:
- Use AI and automation to improve recovery while protecting borrower relationships
- Embed compliance and responsible engagement into borrower interactions
- Connect collections strategy with broader business objectives
- Track meaningful success metrics beyond recovery rates
Whether you’re modernising operations, improving NPA outcomes, or designing a scalable collections infrastructure, this guide outlines the strategies, technologies, and operating considerations banks should evaluate when modernising debt collections.
Why Banks Need to Reinvent Debt Collections
For decades, collections operated as a back-office function centred on late-stage recoveries, manual call queues, and fragmented compliance processes. That model no longer fits today’s lending environment, where debt collection software is increasingly used to connect recovery workflows, borrower intelligence, and operational controls.
The growth of digital lending, expanding unsecured portfolios, and tighter regulations have exposed the limitations of traditional collection approaches. Banks now manage larger volumes of delinquency risk across diverse borrower segments, servicing channels, and compliance frameworks, increasing the need for debt collection management software that can coordinate these processes at scale.
At the same time, borrower expectations have changed. Customers increasingly expect digital interactions, flexible repayment options, and personalised engagement. Regulatory requirements place greater emphasis on transparency, appropriate communication, consent and data governance, and auditability. Leadership teams expect stronger recoveries without compromising customer relationships or operational control, making a collections management platform for banks increasingly relevant to modern recovery operations.
Yet many collection systems remain static, siloed, and dependent on manual intervention.
This aligns with broader World Bank guidance, which highlights structured recovery frameworks, early intervention, and transparent creditor processes as critical components of effective debt resolution systems.
This shift is built around three changes:
- Borrower intelligence instead of static recovery lists.
- Personalised engagement instead of fixed scripts.
- Workflow orchestration instead of escalation-driven processes.
Several forces are accelerating the need for change:
Economic and Regulatory Pressure
- Economic uncertainty requires more adaptive recovery strategies.
- Rising borrowing costs can increase the need for appropriate affordability assessments.
- Consumer protection standards continue to evolve.
- Banks need stronger controls to demonstrate that collection processes are applied consistently and appropriately.
Digital and Operational Expectations
- Borrowers increasingly expect self-service and digital repayment journeys.
- Manual processes become harder to scale across growing portfolios.
- Legacy systems can create operational inefficiencies and compliance risk.
- Rising collection complexity can increase pressure to improve cost-to-collect through automation and better prioritisation.
A Strategic Business Imperative
Collections outcomes now influence customer retention, brand perception, and long-term profitability. They also generate valuable insights that can strengthen future lending and risk decisions, highlighting the growing importance of collection management in banking as a strategic rather than purely operational function.
Banks modernising collections can use debt collection software for banks to apply automation, better prioritisation, and more targeted borrower engagement, improving recovery performance while reducing manual operational effort.
Collections transformation is therefore more than a technology upgrade. It is an opportunity to connect recovery performance, borrower trust, compliance, and operational effectiveness within a more integrated collections model.
Collections Strategy: How Banks Should Approach Modern Collections
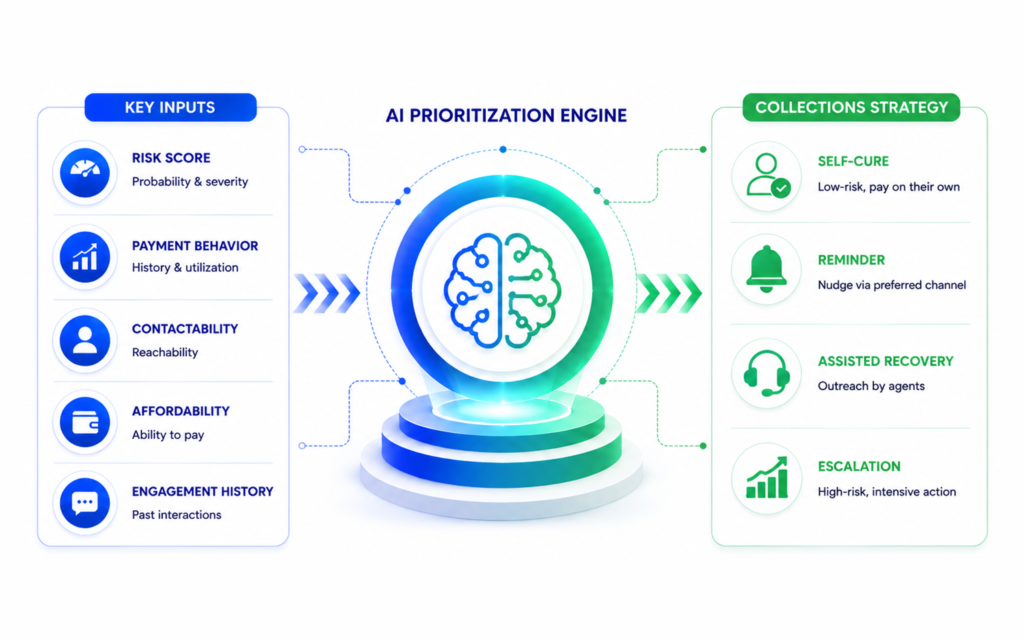
Collections is increasingly being treated as a strategic capability rather than only a recovery function. Modern debt collection software for banks can help institutions balance recovery performance, compliance, operational efficiency, and borrower experience at scale.
The Strategic Shift
Modern collections strategies supported by debt collection management software are built around:
- Behavioral segmentation instead of one-size-fits-all treatment.
- Workflow automation instead of manual follow-ups.
- Structured treatment journeys instead of reactive recovery tactics.
Core Components of a Modern Collections Strategy
Behavioral Segmentation
DPD-based collections remain an important part of recovery operations, but DPD alone may not provide enough context for differentiated treatment.
Banks can segment borrowers using:
- Risk profile and repayment behaviour.
- Delinquency patterns and payment history.
- Product, geography, and economic factors.
This enables more targeted treatment strategies and can support more consistent recovery outcomes through collection management in banking.
Channel Orchestration
Different borrowers may respond to different channels, so channel selection within a collections management platform for banks should reflect factors such as delinquency stage, borrower preferences, risk, and prior engagement.
A progressive engagement strategy typically includes:
- Early-stage accounts: SMS, WhatsApp, email, and self-service reminders.
- Mid-stage accounts: Agent-assisted engagement.
- Higher-risk accounts: Personalised intervention and escalation.
Policy-Driven Treatment Paths
Collections should operate through automated, policy-driven workflows that debt collection software can apply consistently across defined treatment strategies.
Banks should:
- Define escalation paths from reminders to payment plans and, where appropriate, legal action.
- Adapt treatment based on borrower responses and relevant account signals.
- Route cases automatically to specialised recovery teams when required.
Messaging Strategy
Communication should remain clear, personalised, and appropriate to the borrower’s circumstances, risk profile, preferences, and applicable collection policies.
A balance of clarity, empathy, and appropriate firmness can support engagement while protecting customer relationships.
Measuring Success
Key metrics include:
- Early-stage recovery and resolution rates.
- Cost to collect and operational effort.
- Borrower engagement and satisfaction.
- Promise-to-pay conversion.
- Compliance and governance outcomes.
A modern collections strategy connects recovery performance with borrower engagement, compliance, operational efficiency, and long-term portfolio health. The value of debt collection software for banks comes from aligning strategy and execution so that treatment decisions, workflows, channels, and performance measurement work together.
Core Capabilities of Debt Collection Software for Banks
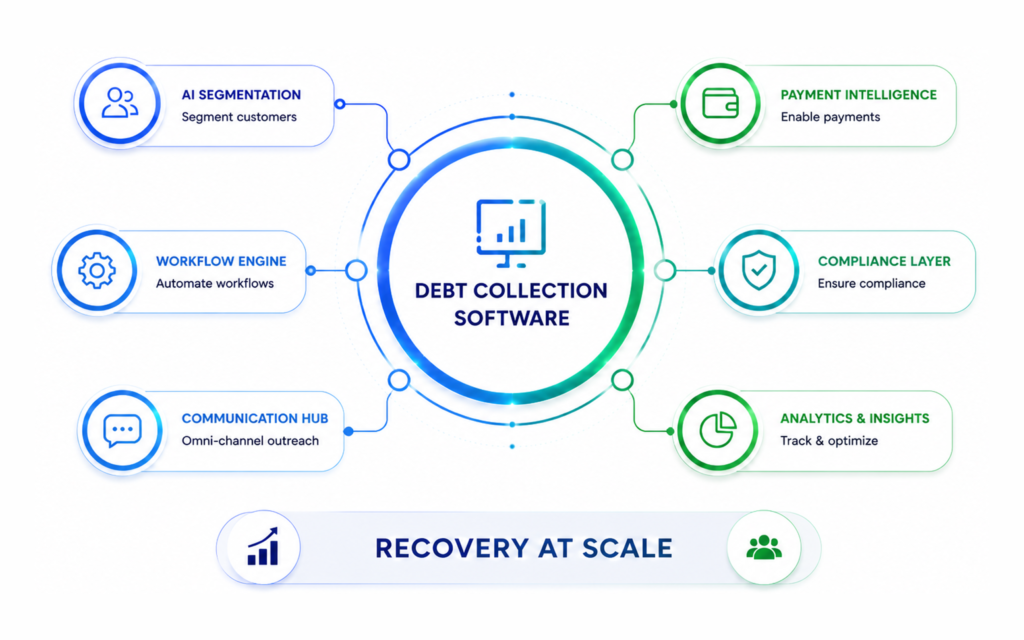
Modern debt collection software for banks has evolved beyond basic reminder systems into platforms that combine automation, analytics, compliance, and borrower engagement.
1. Smart Segmentation
Borrowers can be segmented using:
- Risk profile and repayment history.
- Behavioral patterns and delinquency trends.
- DPD status, geography, and product type.
This enables banks to apply more targeted recovery strategies based on borrower and portfolio characteristics, strengthening collection management in banking through more informed treatment decisions.
2. Omnichannel Engagement
Modern debt collection management software supports coordinated engagement across:
- SMS, WhatsApp, email, IVR, and self-service portals.
- Mobile and in-app notifications.
- Agent-assisted outreach when required.
Using appropriate channels and coordinated engagement journeys can make repayment interactions more accessible and easier to act on.
3. Workflow and Treatment Orchestration
Collections can operate through automated, rule-driven workflows within a collections management platform for banks that:
- Trigger reminders, payment plans, settlements, and escalations.
- Adapt treatment based on borrower responses.
- Route accounts automatically to specialised recovery teams.
- Support segment-specific recovery journeys.
This helps banks apply collection policies consistently and scale treatment workflows across portfolios.
4. Recovery Intelligence
Built-in analytics provide visibility into:
- Recovery performance and trends.
- Agent productivity.
- Borrower responsiveness.
- DPD and segment-level outcomes.
- Compliance adherence.
Continuous monitoring allows banks to refine recovery strategies over time.
5. Unified Collections Operations
A central workspace within debt collection software gives teams access to borrower information, communication history, prioritised work queues, and action tracking from a single interface.
6. Embedded Compliance Controls
Modern platforms can include:
- Audit trails and interaction logs.
- Consent management.
- Dispute resolution workflows.
- Compliance-approved communication templates.
7. Seamless Integration
Integration with LMS, CRM, payment gateways, and core banking systems can support timely data synchronisation across collections operations, helping debt collection software for banks reduce reliance on fragmented workflows.
Banks deploying platforms with these capabilities report:
- 30 to 50 percent improvement in early stage recovery rates.
- 30 to 40 percent reduction in collection costs.
- Higher borrower satisfaction.
- Stronger compliance outcomes.
Together, these capabilities transform collections from a recovery process into a strategic function that protects revenue, improves efficiency, and strengthens customer relationships.
Technology & Architecture: What Banks Need Under the Hood
Modern debt collection software for banks is no longer limited to standalone recovery workflows. It can connect collections with servicing, compliance, risk, and customer engagement through an integrated technology architecture.
As portfolios expand and regulatory requirements evolve, technology architecture increasingly influences operational efficiency, scalability, data availability, and the ability to execute collections strategies consistently.
Core Technology Foundations
Cloud Native Infrastructure
Modern debt collection management software can use cloud-native architecture to scale collection operations dynamically and support availability, resilience, and performance as portfolio volumes fluctuate.
API First Connectivity
Collections depend on continuous data exchange across LMS, core banking systems, payment gateways, credit bureaus, and communication channels. API-driven integration within a collections management platform for banks can support real-time synchronisation and reduce reliance on fragmented data and operational workflows.
Real Time Processing
Borrower actions such as payments, settlements, or restructuring requests can trigger timely updates to balances, workflows, treatment paths, and recovery actions, helping reduce delays and manual intervention.
Scalable Data Architecture
Collection platforms must support large volumes of operational, behavioural, and compliance data while maintaining appropriate access performance, secure storage, and audit readiness.
Intelligence Layer
The intelligence layer within debt collection software adds decisioning and analytical capabilities that can support more differentiated collections strategies.
- Machine learning models can predict repayment likelihood and engagement behaviour.
- Behavioural scoring engines can segment borrowers beyond simple DPD classifications.
- No-code decision engines can allow collection teams to configure and refine treatment strategies with less reliance on development resources.
Together, these capabilities can support more precise treatment decisions and continuous strategy optimisation.
Security & Compliance by Design
Given the sensitivity of borrower information, enterprise collection management in banking platforms should provide controls such as:
- End-to-end encryption.
- Role-based access controls.
- Comprehensive audit trails.
- Consent management and appropriate regulatory safeguards.
These controls can help reduce operational and compliance risk while improving transparency and governance.
Future Ready Architecture
Technology roadmaps for modern collections environments may include:
- AI-powered virtual assistants for borrower engagement.
- Predictive analytics that can identify potential delinquency risks before missed payments occur.
- Open banking integrations that can support affordability assessments and personalised repayment plans, where appropriate and permitted.
- Microservices-based architecture that can support modular development and scaling.
These capabilities can give banks greater flexibility to respond to changing borrower behaviour, regulatory expectations, and market conditions while supporting more adaptable collection management in banking.
Banks investing in modern collection architecture report 30 to 50 percent higher early stage recovery rates and 30 to 40 percent lower collection costs through better automation, intelligence, and workflow orchestration.
Collection architecture is both a technology and strategic consideration for banks. A well-designed architecture can provide the foundation for scalable recovery operations, stronger controls, better borrower experiences, and long-term operational performance.
Compliance, Controls & Regulator Readiness
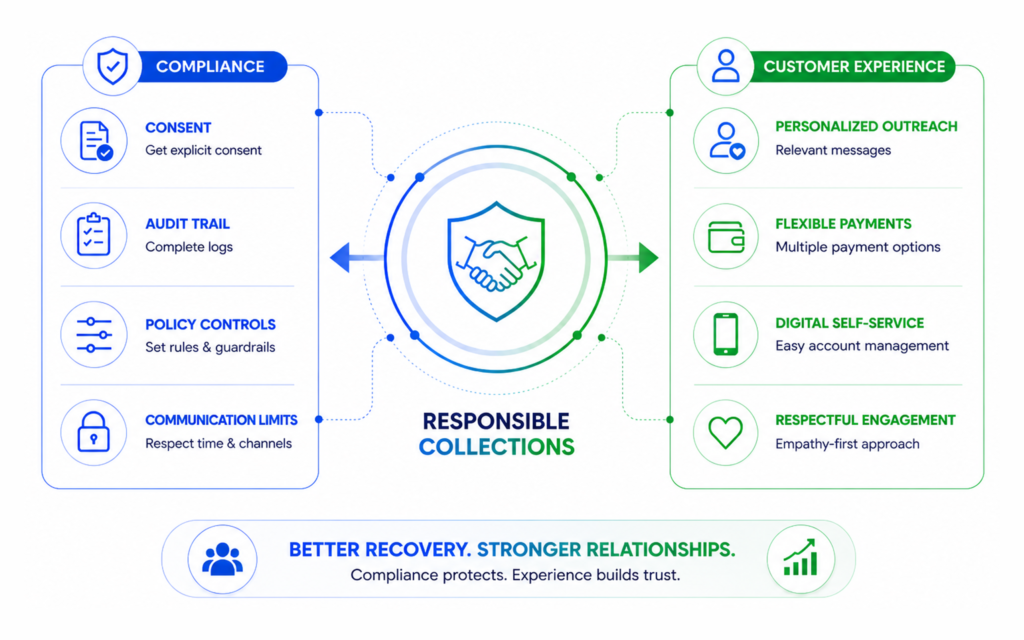
As collections become increasingly digital, compliance has become a strategic requirement alongside operational control. Banks should embed applicable regulatory safeguards directly into collection workflows so that actions can be appropriately controlled, traceable, auditable, and borrower-centric.
Borrower Communication Governance
Collection requirements vary by jurisdiction, but banks generally need appropriate controls over borrower communications across channels such as SMS, WhatsApp, IVR, email, and agent-assisted interactions. These controls should support transparency, applicable communication requirements, recordkeeping, and auditability within debt collection software for banks.
Enterprise debt collection management software should support controls such as:
- Approved communication templates and escalation paths.
- Contact-frequency and timing controls.
- Complete interaction logs across channels.
Consent, Privacy & Data Controls
India’s Digital Personal Data Protection framework places greater emphasis on how organisations manage personal data, consent, and related data-governance obligations.
Banks should have controls within their collections management platform for banks to manage:
- Consent records with appropriate timestamps, versioning, and auditability.
- Channel preferences and communication permissions.
- Do-not-contact requests and applicable contact restrictions.
- Third-party collection agencies operating within defined data-governance and communication requirements.
Security, Risk & Compliance Alignment
Collections platforms should support security and control requirements appropriate to the bank’s operating and regulatory environment, including:
- End-to-end encryption.
- Role-based access controls.
- Continuous monitoring and anomaly detection, where appropriate.
- Integration with relevant KYC, AML, and sanctions-screening frameworks.
These controls can help protect borrower data and reduce operational and regulatory risk when supported by appropriate governance and implementation practices.
Dispute Resolution & Audit Readiness
Borrower disputes can have compliance, operational, and customer-service implications and should be managed through structured processes.
Structured workflows, audit trails, and escalation paths can help banks manage complaints consistently and maintain an evidence trail. A well-designed collections environment should also make it possible to retrieve relevant consent records, communication histories, agent actions, and resolution timelines when required for reviews or audits, supporting stronger collection management in banking.
Customer Experience in Collections: Designing Lower-Friction Borrower Journeys
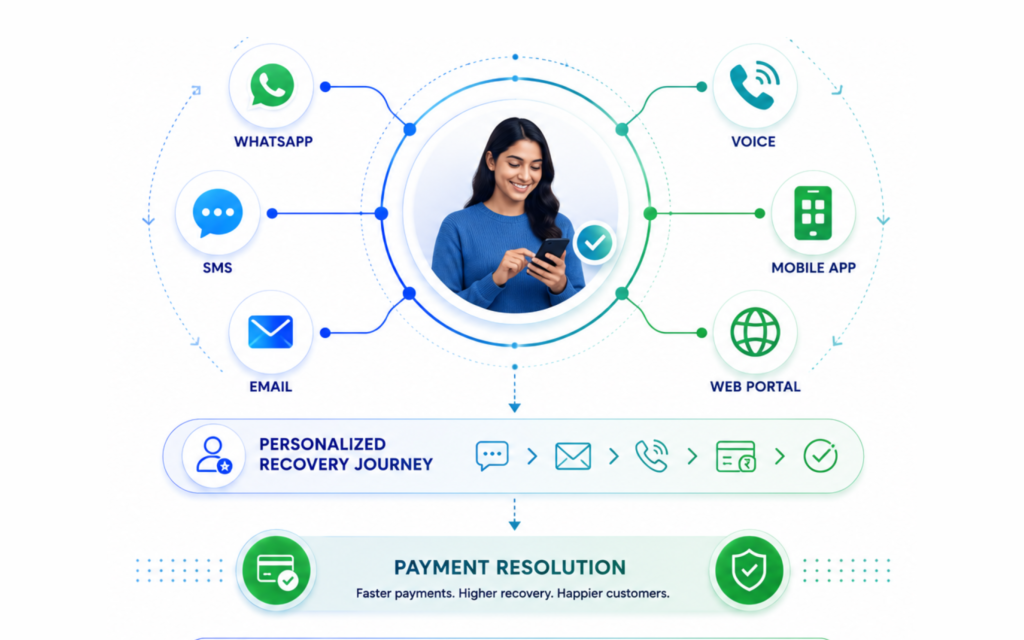
Collections is an important customer touchpoint. Traditional approaches, built around repetitive calls, rigid processes, and one-size-fits-all treatment, can create frustration, lower engagement, and weaken recovery outcomes. Modern debt collection management software can help banks design more contextual and borrower-centric collection journeys.
A modern collections approach looks beyond overdue balances to the barriers that can prevent repayment. Banks can design borrower journeys that make repayment easier to understand, access, and complete while encouraging appropriate engagement.
Common repayment friction points include:
- Irregular income patterns that make fixed repayment schedules difficult.
- Complex payment journeys and poor mobile experiences.
- Limited flexibility for part payments or repayment arrangements.
- Generic or overly aggressive communication that discourages engagement.
- Fragmented views of dues across multiple products.
- Lack of transparency around repayment options and potential credit impact.
A collections management platform for banks can help address these issues by connecting borrower context, repayment options, communication preferences, and collection workflows in a more coordinated experience.
Modern collections platforms can address these friction points through flexible payment plans, self-service repayment journeys, personalised communication, consolidated borrower views, and intelligent workflow automation. A collections management platform for banks can bring these capabilities together across borrower segments, channels, and repayment journeys.
To evaluate the customer experience during collections, banks can track how collection management in banking affects borrower engagement and recovery outcomes, including:
- NPS and CSAT during recovery.
- Digital journey completion rates.
- Promise-to-pay conversion.
- Post-delinquency retention.
The results are compelling:
- 34 percent higher recovery rates in early stage delinquency.
- 45 percent reduction in manual call volumes.
- 50 percent improvement in borrower engagement.
- Stronger customer loyalty and long term retention.
Empathy and operational efficiency do not have to be competing priorities. When collections become easier to understand, more transparent, and more borrower-friendly, banks can support both a better customer experience and more effective recovery processes.
Predictive collections can extend the borrower journey beyond reactive recovery by identifying accounts that may be at higher risk of delinquency before a missed payment occurs.
This approach transforms potential defaults into relationship-strengthening opportunities through:
- Proactive Financial Wellness Outreach: Engaging customers before they miss payments
- Affordability-Based Solutions: Offering restructuring options based on real-time financial assessment
- AI-Powered Conversational Interfaces: Using virtual assistants that understand borrower intent and respond with empathy
Key Trends Shaping Modern Banking Collections
From Basic SMS to Intelligent Engagement
Collections communication can move beyond one-way reminders toward contextual, two-way conversations. Digital collections strategies may incorporate WhatsApp payments, multilingual messaging, dynamic content, and real-time engagement journeys where appropriate.
The goal is to reduce borrower fatigue and make repayment actions easier to understand and complete, particularly during early-stage delinquency.
AI Must Be Explainable
The conversation around AI has moved beyond automation to accountability.
Boards and risk teams increasingly need visibility into how AI-assisted decisions are made, whether models are appropriately governed, and how outcomes can be reviewed or challenged. Explainability, audit trails, decision records, and override tracking can therefore form important components of responsible AI governance in debt collection software.
Behavioural Science in Collections
Behavioural science can inform collections strategies designed to improve borrower engagement and make repayment actions easier to understand and complete.
Techniques such as nudging, progress-based messaging, and carefully designed framing can encourage repayment behaviour without unnecessarily increasing collection pressure.
Behavioural design can therefore be a useful area for banks evaluating ways to improve borrower engagement while maintaining appropriate collection practices.
Digital First, Human When Needed
Digital engagement can handle routine collections interactions at scale, while complex, sensitive, or higher-risk borrower situations may require human intervention.
The emerging model combines self service and automation with intelligent agent intervention at critical moments such as disputes, hardship requests, or restructuring discussions. Debt collection software for banks can support this hybrid model by coordinating automated journeys with appropriate human intervention. This approach can improve resolution rates while maintaining operational efficiency.
Compliance by Design
Regulatory expectations continue to rise across frameworks such as the DPDP Act, RBI Fair Practices Code, and global privacy standards.
Leading banks are embedding compliance directly into collection architecture through consent management, contact governance, DPD aware workflows, audit trails, and data minimisation controls. The objective is no longer simply being compliant, but proving compliance instantly when required.
What Boardrooms Are Really Discussing
The collections transformation debate is no longer about whether change is required. The focus has shifted to how effectively banks can balance efficiency, empathy, and auditability.
The institutions leading today are those treating customer experience, compliance, and recovery performance as interconnected outcomes rather than competing priorities.
Niche Use Cases and Configurations
Modern debt collection software for banks can be configured for different portfolio, borrower, and operating models.
- High-Value Borrowers – Relationship-led workflows can route cases to senior recovery teams or Relationship Managers, prioritising restructuring and engagement before escalation. This approach can help preserve long-term customer value while supporting voluntary recovery.
- Retail & Digital Lending Portfolios – High-volume portfolios such as credit cards, BNPL, and personal loans can use automated DPD-based journeys, chatbot engagement, and self-service repayment options through debt collection management software to support collections at scale and manage cost to collect.
- Co-Lending Collections – Platforms can support shared recovery responsibilities through role-based workflows, data exchange, and audit-ready tracking across lending partners.
- Digital-First Lending Models – Collections can be embedded directly into mobile and digital experiences through in-app reminders, payment journeys, behavioural nudges, and automated escalation logic. This model can reduce unnecessary manual intervention for routine collection journeys while allowing appropriate cases to be escalated to human teams.
- Secured vs. Unsecured Portfolios – Different treatment paths can be configured for secured and unsecured products, balancing asset protection, recovery timelines, applicable legal actions, and customer experience requirements.
- Behaviour-Based Collections – Advanced segmentation can differentiate first-time late payers from repeat delinquents using payment history, engagement patterns, and relevant risk indicators. This can support differentiated journeys for borrowers experiencing temporary repayment difficulties and earlier intervention for persistent delinquency as part of collection management in banking.
These specialised configurations allow banks to align recovery strategies with borrower behaviour, product characteristics, and business objectives while supporting operational efficiency, appropriate borrower treatment, and compliance controls.
Analytics & Intelligence: Beyond Reporting
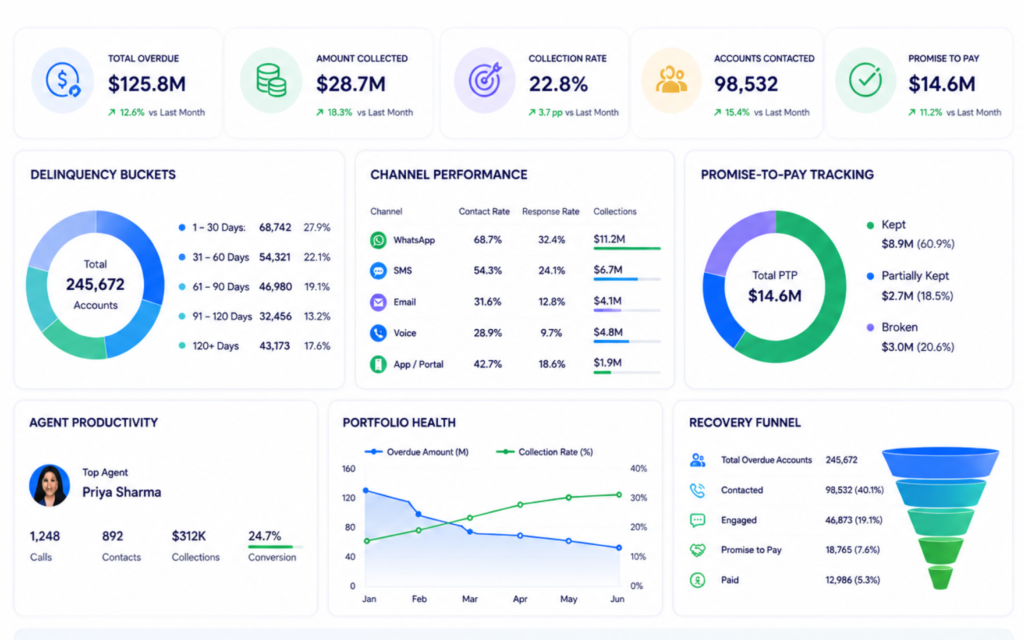
Modern collections require more than dashboards. They require analytics and intelligence that help banks understand portfolio behaviour, identify emerging issues, and make more informed collection decisions through debt collection software.
Real Time Visibility
Move beyond historical reports to current insights on borrower behaviour, campaign effectiveness, team productivity, and recovery performance. The focus shifts from what happened to what requires attention now.
Predictive Recovery Intelligence
AI-driven models can estimate repayment likelihood, engagement risk, and channel preferences, supporting earlier intervention before accounts deteriorate further.
OECD research notes that financial institutions are increasingly using AI to improve decision quality, automate operational processes, and strengthen risk management. These broader applications provide context for the growing use of predictive approaches in financial-services operations.
Continuous Performance Optimisation
Payment activity, borrower responses, and journey drop-offs can provide learning signals that help banks refine messaging, workflows, channels, and treatment strategies based on observed outcomes.
Portfolio Level Intelligence
Banks can benchmark performance across products, geographies, and borrower segments, identify emerging risk trends, and support forecasting of delinquency movements through a collections management platform for banks.
Embedded Compliance Analytics
Monitor communication frequency, consent-related controls, dispute handling, and applicable collection controls through real-time, audit-ready visibility.
The result is a more informed collections operation in which portfolio data and observed outcomes can support faster decisions, continuous optimisation, stronger operational control, and more consistent compliance processes with debt collection software for banks.
Banks That Made the Shift
Large Private Bank | Retail Lending
Managing over 10 million borrowers, the bank faced fragmented collections, inconsistent follow ups, and weak early stage recoveries. By implementing a centralized debt collection software platform with AI driven segmentation and dynamic treatment paths, it achieved:
- 37% increase in early bucket recoveries
- 50% reduction in agent follow up costs
- 100% audit visibility across collection journeys
PSU Bank | Rural Agri & MSME Portfolios
Limited digital adoption, language barriers, and costly field operations constrained recoveries. The bank introduced geo tagged agent workflows, multilingual IVRs, and consent driven collection processes.
- 33% reduction in legal escalations
- 2.5x improvement in first time field resolutions
- Stronger audit readiness through automated contact logging
Digital NBFC | Embedded Credit
Serving borrowers through 40+ consumer apps, the NBFC struggled with rising first time delinquencies and post default churn. It deployed embedded collections with in app reminders, one click settlements, and AI driven engagement.
- 72% resolution within 72 hours
- Less than 6% churn after delinquency
- Collections became a customer experience differentiator
Public Sector Bank | Mortgage Collections
Legacy processes made hardship management slow and expensive. The bank adopted rule based treatment planning, proactive deferral journeys, and borrower segmentation.
- 2x increase in voluntary part payments
- 40% reduction in field visits
- 32% reduction in legal escalations
Future of Banking Collections: What’s Next?
Collections is no longer a back office recovery function. It has become a strategic capability that sits at the intersection of risk, customer experience, compliance, and profitability.
Borrowers expect personalized engagement. Regulators demand transparency. Boards want stronger recoveries without increasing operational complexity or reputational risk.
Yet many institutions still rely on fragmented tools, manual workflows, and reactive escalation models that were never designed for today’s lending environment.
The leaders are taking a different path. They are moving from recovery management to recovery intelligence, using data, automation, and real time decisioning through debt collection management software to intervene earlier, engage smarter, and recover more effectively.
This is where collect.ezee is redefining modern collections.
Built as an AI powered, no code debt collection platform, ezee.ai helps banks move from reactive follow ups to predictive, adaptive, and ROI driven recovery operations with debt collection software for banks. It combines borrower intelligence, recovery automation, compliance control, and portfolio visibility in a single platform.
Using behavioral signals, repayment patterns, DPD status, and interaction history, collect.ezee automatically segments borrowers and orchestrates the right treatment strategy. AI driven capabilities such as Right Channel to Interact (RCI), Right Time to Interact (RTI), sentiment analysis, transcript intelligence, and AI voice agents help institutions engage borrowers with greater precision and effectiveness.
The platform enables business teams to configure collection strategies, automate workflows, personalize communication, manage agencies, allocate workloads intelligently, and monitor performance through real time dashboards without dependence on technology teams, supporting collection management in banking at scale.
The future of collections will belong to institutions that combine intelligence, automation, compliance, and empathy at scale. collect.ezee gives them the platform to do exactly that.
Frequently Asked Questions
Debt collection software for banks is a centralized system that automates recovery workflows across delinquency buckets, channels, and teams. It can ingest account data from LMS and core banking systems, prioritize cases using rules or AI, and orchestrate reminders, calls, field visits, and other recovery actions. In practice, it can trigger SMS or WhatsApp journeys when an account reaches a defined DPD threshold, allocate higher-risk SME accounts to appropriate collection teams, and support payment settlement through integrated gateways.
Digital debt collection in banking means managing recoveries through automated, self-service, and omnichannel journeys supported by debt collection management software, instead of relying only on manual phone calls and field visits. It can use apps, web portals, UPI links, WhatsApp, and email to let borrowers view dues, explore repayment options, and make payments digitally. For example, a retail borrower can receive a personalised reminder with a promise-to-pay link instead of a call-centre script.
AI can support debt collection by estimating who is likely to pay, when engagement may be most effective, and which communication channel may be appropriate. Models can use lending history, repayment behaviour, and other relevant signals to prioritize queues and recommend next-best actions. In practice, banks can use these insights to support earlier intervention for accounts showing signs of repayment risk while offering digital repayment options to appropriate late-paying borrowers.
Analytics in a collections management platforms for banks can turn delinquency data into insights on roll rates, contact effectiveness, and portfolio risk. Leaders can use dashboards to monitor bucket movements, campaign performance, and agent productivity rather than relying only on static MIS reports. For example, a bank can compare the performance of IVR, WhatsApp, and email journeys for different delinquency segments and adjust collection strategies based on observed results.
Banks can use predictive models to flag borrowers who may be at higher risk of missing payments before delinquency progresses. Depending on the data available, models can consider repayment history, utilization patterns, bounced debits, engagement behaviour, and other relevant risk signals to generate early-warning indicators. An auto-loan borrower showing signs of repayment stress, for example, could be considered for an earlier reminder, engagement, or appropriate repayment-support journey.
- Debt collection software for banks can support recoveries while reducing manual calls, cost-to-collect, and operational risk through standardized playbooks and automation.
- Reduces human error and helps enforce policy consistently across buckets, products, and regions.
- Provides management information on roll rates, bucket movement, and collector productivity for faster course correction.
- Lets automated reminders handle routine early-bucket accounts while agents focus on higher-value, higher-risk, or exception cases.
- Creates a consistent framework for monitoring collection performance, borrower engagement, and operational controls.
- Groups borrowers using relevant risk, repayment intent, and behavioural signals rather than relying only on DPD or ticket size.
- Enables differentiated strategies for segments such as borrowers showing temporary cash-flow pressure, persistent delinquency, or repeated missed payments.
- Routes lower-risk segments to softer, digital-first journeys while reserving human or specialist intervention for higher-risk, complex, or dispute-prone cases.
- Can help reduce unnecessary negative interactions while giving collection teams more context for selecting appropriate treatment strategies.
Banks typically integrate collections platforms with LOS, LMS, and core banking systems through APIs, message queues, or other governed integration mechanisms so account, payment, and status data can be exchanged between systems. The collections system can consume loan schedules, repayments, and delinquency or NPA indicators, then return status and promise-to-pay updates to connected systems. This can provide a more consistent delinquency view across digital, call-centre, and field teams, subject to the bank’s integration, security, and governance requirements.
- Configurable workflows, rule engines, and strong API integrations with LMS/core, CRM, and digital channels.
- AI-driven segmentation, risk-based queues, and “smart workflows” instead of spreadsheet-led allocation.
- Omnichannel communication (SMS, WhatsApp, email, app, IVR, field) with contact rules and audit trails for compliance.
- Deep LMS/core integration, payment gateway connectors, field-app support, digital notices, and legal-case tracking in one system.
- Robust compliance controls, consent management, and field tracking appropriate for retail, SME, and other relevant portfolios.
Safe migration involves cleaning and mapping legacy data, running trial loads, and reconciling sample portfolios before full cutover. Banks can migrate active and closed accounts with relevant contact, DPD, and repayment history while preserving required audit trails. A phased rollout can include parallel validation, performance comparison, and controlled transition from the existing collections environment. Data governance, encryption, access controls, and reconciliation should be incorporated into the migration plan according to the bank’s security and regulatory requirements.
References
- Reserve Bank of India — Outsourcing of Financial Services: Responsibilities of Regulated Entities Employing Recovery Agents
- Reserve Bank of India — Guidelines on Digital Lending
- Reserve Bank of India — Public Repository of Digital Lending Apps
- World Bank — Insolvency and Debt Resolution
- World Bank — Principles for Effective Insolvency and Creditor/Debtor Regimes
- OECD — Regulatory Approaches to Artificial Intelligence in Finance
- OECD — Supervision of Artificial Intelligence in Finance: Challenges, Policies and Practices
- Government of India — Digital Personal Data Protection Act, 2023